Africa's missing middle is a mispriced market, and the Caribbean has the same gap
Aruwa Capital is raising its second fund to lend growth equity to businesses too big for microfinance and too small for private equity. The model carries lessons for islands with the same shortfall.
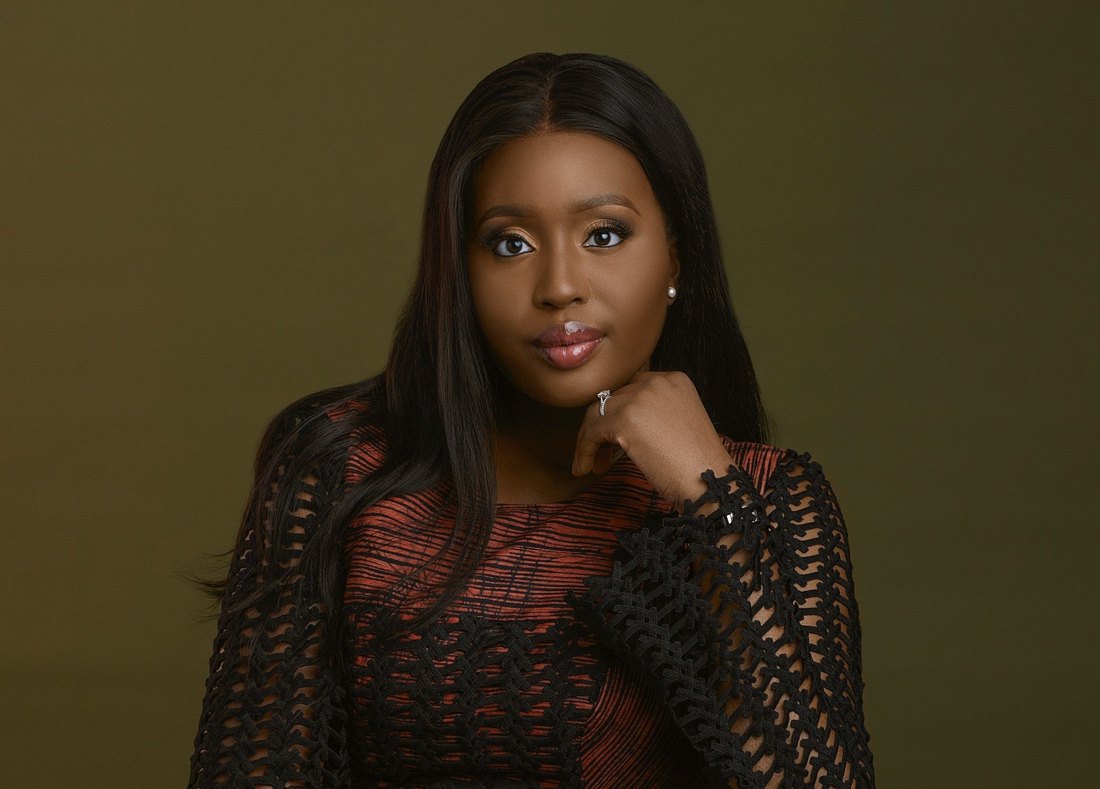
LAGOS. Every emerging market has a shelf of businesses that are too large for microloans and too small for private equity. They have revenue, customers and a clear path to growth, but the capital they need sits in a gap that most investors have decided is not worth their time.
Adesuwa Okunbo-Rhodes, founder of Aruwa Capital Management, calls this space the "missing middle" and makes a simple claim about it: "The industry calls it the 'missing middle'. I call it the largest mispriced opportunity on the continent."
Her firm invests between $1 million and $3 million in women-led and women-focused small and medium enterprises in Sub-Saharan Africa. For a Wall Street reader, the thesis is familiar. A market that prices a segment as unattractive will leave returns on the table for anyone willing to build the machinery to underwrite it.
Her own career is part of the argument. She left a six-figure salary at J.P. Morgan to make smaller investments, a move most of her former colleagues would not make. In her words, "I left a six figure salary at J.P.
Morgan to write smaller cheques in markets most investors won't touch. People then thought I'd lost my mind." Bankers rarely walk away from the largest tickets, which is why the decision stands out.
The second fund, Aruwa Capital Fund II, targets $50 million with a $60 million hard cap. The most useful detail is how it is financed. As reported by Launch Base Africa, the International Finance Corporation (IFC) committed equity of up to $8 million, capped at 20% of total commitments, and a $3 million subordinated co-investment through its Concessional Capital Window. The IFC also provides capacity-building support for the fund manager and its portfolio companies.
That structure matters more than the headline. A public anchor takes a concessional layer and absorbs part of the early risk, which allows private investors to commit to a fund that would otherwise look too unfamiliar. The fund then earns its returns from growth equity in consumer goods, financial services, healthcare and life sciences, and renewable energy. Fund II's first three portfolio companies, Yikodeen, Toasties and Onechek, are all consumer businesses, and Fund I includes FairMoney, KoolBoks, Lifestore Pharmacy, OmniRetail and Wemy Industries.
Okunbo-Rhodes says the firm now has 16 portfolio companies, and she points to gross margins above 40% as evidence that the businesses are sound. Her summary of the returns case is blunt: "Returns and impact were never a trade-off. That framing was always lazy."
The Caribbean has its own missing middle. Island businesses in agro-processing, logistics, health services, tourism-linked services and renewable energy often need $1 million to $3 million to expand. Banks are cautious about lending at that size without collateral, and regional private equity rarely reaches so far down the market. The shortfall is the same, even if the scale and the currencies differ.
The Aruwa model suggests three questions for Caribbean policymakers and investors. The first is who will anchor the fund. A regional development bank could play the role that the IFC plays in Aruwa's second fund, taking a concessional layer that makes private money willing to follow. The second is scale.
A single island rarely produces enough investable companies to justify a dedicated fund, so any Caribbean version would need to pool deals across several CARICOM markets. The third is currency risk. Many Caribbean currencies are pegged to the US dollar, which removes the naira-style devaluation risk that Nigerian funds face, but it leaves the dollar-borrowing risk discussed in our recent coverage of the Federal Reserve. A fund with dollar capital and local-currency earnings needs careful hedging, or it will be exposed to the very cost of money it is trying to avoid.
There is also a question the region should answer with data before it designs anything. Aruwa's gender lens is a specific mandate, and the logic behind it is that women-led firms are screened out by credit models that are not built for them. Whether the same pattern holds for women-led businesses on the islands is an empirical question. A fund should not be built on an assumption that a regional study could test.
The missing middle is not a charity case. It is a pricing error, and pricing errors close when someone builds the machinery to see them. Okunbo-Rhodes frames her strategy as "not as charity but commercial growth equity that happens to close one of the most stubborn gaps in the market."
That is the right way for Caribbean investors to think about the same gap at home. The question is not whether the opportunity exists. It is who will be willing to underwrite it first.
Read more at The Caribbean Ledger ›