Bermuda bets on becoming the world's first on-chain economy
The island that built a global reinsurance hub out of nothing but law and trust is trying the same move again, this time with digital assets.
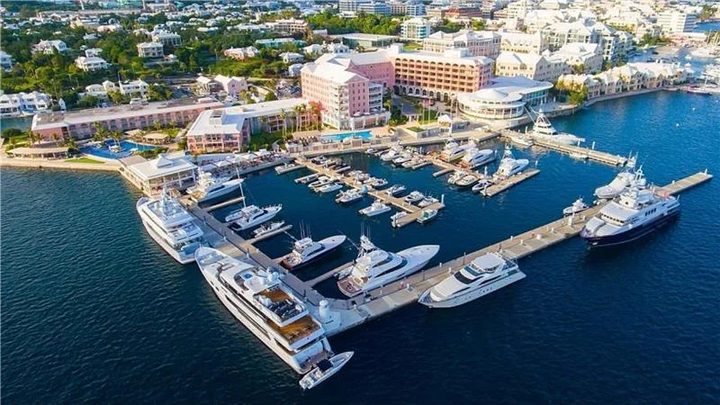
HAMILTON. Bermuda has made a career out of selling certainty. With no oil, little land and a population of about 64,000, the island built one of the world's leading reinsurance centers on the strength of its regulation, its courts and its reputation for taking financial supervision seriously. It is now trying to repeat that trick in digital assets, with an ambition few jurisdictions of any size have stated out loud: to become the world's first fully on-chain national economy.
The plan was set out at the start of the year, when the Government of Bermuda announced, with support from the stablecoin issuer Circle and the exchange Coinbase, that it intended to move the machinery of a national economy onto public blockchains. The island has spent the years since building the legal scaffolding, having passed digital-asset and initial-coin-offering legislation early enough to be one of the first movers among small jurisdictions, and Premier David Burt has carried the message to blockchain and policy summits in the United States and beyond under the banner of what Bermuda calls its regulatory standard.
The logic is the reinsurance logic, updated. A small island cannot win on scale, so it wins on rules. By writing clear digital-asset law before larger economies did, and by supervising the firms that register under it the way it supervises its insurers, Bermuda offers something the sector prizes and rarely finds: a stable, English-common-law home with a regulator that answers the phone. If the bet works, it draws registrations, jobs and fees in the same way the reinsurance industry did, without the island having to manufacture or mine anything.
The risks are equally clear, and Bermuda has watched other jurisdictions learn them. Digital assets are volatile, the firms that dominate them rise and fall quickly, and a reputation for sober regulation can be spent faster than it was earned if a single large registrant fails badly. Tying a national economy's plumbing to public blockchains also raises questions, from consumer protection to the resilience of the networks themselves, that no country has yet answered at national scale, precisely because none has gone first.
What on-chain actually means in practice is narrower than the slogan. It is regulated stablecoins used for settlement, tokenized versions of conventional assets, and public-ledger record-keeping for parts of the financial plumbing, all under the supervision of the Bermuda Monetary Authority. The island is not proposing to gamble its reserves on volatile tokens. It is proposing to be the trusted address where the regulated version of this industry is domiciled, which is the same model, moved to a new asset class, that built its insurance business.
For a territory that usually appears in regional coverage only for a hurricane or a cruise statistic, the on-chain project is a genuinely distinctive wager. It is the clearest current example of a Caribbean jurisdiction trying to turn the AI-and-crypto era's appetite for regulated, trustworthy venues into a line in its own budget, the same instinct that led Anguilla to monetize a domain suffix, pursued here through law rather than luck. Whether Bermuda becomes the world's first on-chain economy or merely one of its better-regulated digital-asset centers, the island is doing what it has always done: selling the one thing it has in abundance, which is credibility, to a market that has learned the hard way how scarce that is.
Read more at The Caribbean Ledger ›