When the bell goes quiet: Scotia leaves the exchange it helped build
The Supreme Court has cleared Scotiabank to take Scotia Group Jamaica private. On Monday the ticker goes dark after more than 57 years, minority holders bank 75 dollars a share, and the Jamaica Stock Exchange loses close to one in every nine dollars it lists. A St. Jean Money & Markets analysis.
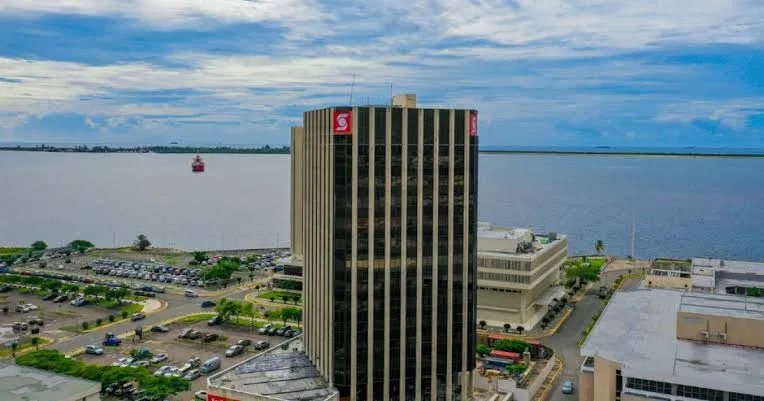
KINGSTON. On Monday morning, November 2, the Jamaica Stock Exchange will open for business without Scotia Group Jamaica for the first time in more than 57 years. The shares will be suspended, the ticker that generations of Jamaican investors watched will go quiet, and one of the oldest and largest names on the exchange will pass into private hands. On Friday, October 30, the Supreme Court of Jamaica sanctioned the scheme of arrangement that makes it so, and with that ruling a bank that has been part of Jamaican life since 1889 ends its public listing.

This is a St. Jean Money & Markets analysis of what that means: for the shareholders who are being paid, for the exchange that is being thinned, and for the other large companies now quietly asking whether they should do the same.
The terms of the exit
The mechanics are settled. Justice Althea Jarrett sanctioned the scheme on October 30, as the Jamaica Observer reported, and once the order is filed with the Companies Office of Jamaica, Scotia Group Jamaica becomes a wholly owned subsidiary of Scotiabank. Scotiabank Caribbean Holdings Limited will pay 63.50 billion Jamaican dollars, about 397.84 million US dollars, to buy out the minority shareholders at 75 dollars a share, with payment due within 10 business days, by November 13. Those holding more than 13,333 shares must set up mandatory payment instructions through the Jamaica Central Securities Depository, because cheques above 1 million dollars have not been issued since September 1.
From Monday, November 2, the shares stop trading, and once payment is complete the company will apply to delist.
Since 1889
To understand what is leaving, start with how long it has been here. The Bank of Nova Scotia opened a branch in Kingston in 1889, when banking on the island was barely 50 years old, and it stayed through the earthquake of 1907 and through independence in 1962, growing into an institution with 28 branches and more than 2,000 employees today, according to Scotiabank's own history. When the Jamaica Stock Exchange began trading on February 3, 1969, then called the Kingston Stock Exchange, Scotia's Jamaican operation was among the pillars the young market organized itself around, and it has traded publicly for more than 57 years, nearly the entire life of the exchange. For most Jamaicans alive today, a listed Scotia is simply a fact of the financial landscape, as fixed a feature as the Scotiabank Centre in downtown Kingston.
On Monday that fact changes.
The listing that is ending is Scotia Group Jamaica Limited, the holding company that sits above the bank and its insurance and investment arms, led by President and Chief Executive Audrey Tugwell Henry. The bank itself is not going anywhere. Branches will open Monday, staff will report, and customers will bank as before. What ends is public ownership, the right of an ordinary Jamaican to buy a share of one of the country's largest financial institutions and share in its profits.
That right has existed for more than half a century. After this week it will not.
What the shareholders got
For the minority shareholders being bought out, the deal is a good one, and it is worth saying so plainly. The offer of 75 dollars a share sits above the 70.11 dollars at which the stock closed on October 30, a premium of roughly 7% to the last traded price, and it comes after a year in which the shares had already climbed 32% so far in 2026, according to St. Jean Money & Markets. A holder who owned Scotia through the year is being handed a further premium on top of a strong run, in cash, with payment guaranteed by court order inside two weeks.
At the October 7 shareholder meeting, 80.16% of the minority holders present voted in favor, representing 97.70% of the units cast, a firmer endorsement than the 77% the preliminary count had shown. Shareholders, in short, were offered a price most of them judged fair, and took it.
The harder question is what those shareholders do next. Many are pension funds and ordinary Jamaican savers who held Scotia precisely because it was large, liquid, and paid a dependable dividend, the kind of holding you buy and forget. They are about to receive cash they must put somewhere, in a market with one fewer blue-chip anchor than it had the week before. Some of that money will rotate into other listed Jamaican companies, which the market needs.
Some will sit in bank deposits that, with the Federal Reserve holding its rate high, pay more than they used to but less than Scotia did. And some will simply leave the local market altogether. Where it goes is one of the quieter stakes in this story, because a cash-out is only good for an exchange if the cash comes back to it.
What the exchange loses
Then there is the exchange itself. Scotia Group Jamaica closed October 30 with a market capitalization of about 218.15 billion Jamaican dollars, according to St. Jean Money & Markets. Against a total Jamaican market capitalization of roughly 1.89 trillion dollars across the exchange's 95 listed companies as of the same date, Scotia alone accounted for close to one in every nine dollars of value on the market.
Remove it, and the listed value of the Jamaican market falls by that share in a single step, not because any wealth has been destroyed, but because it has moved from public hands into private ones. By SJMM's reading of the exchange, the market has risen 18.6% so far this year and 12.8% over the past 12 months, so it absorbs the loss from a position of strength. It absorbs it all the same, and it will carry a visibly smaller listed value into November than it carried into October.

There is a quiet irony in the tape from Scotia's last full day of trading. The JSE Index advanced 794.50 points, or 0.21%, on Friday, October 30, to close at 385,199.03, with 26 of the 63 stocks traded advancing, 23 declining and 14 holding firm, according to St. Jean Money & Markets, drawing on the Jamaica Stock Exchange trade summary. The market, in other words, had a good day.
Scotia did not join it. Its shares slipped 0.89%, or 63 cents, to close at 70.11 dollars on volume of just 42,633 units, a stock marking time at a price the fixed buyout had already decided. The index will not fall when Scotia leaves, because an index tracks the prices of the shares that remain, not the ones that go. What shrinks, out of sight of the daily number, is the pool of value the public is allowed to own.

Size is not the only thing that leaves with Scotia. An anchor listing is a reference point: a stock that index funds must hold, that analysts cover, that sets a benchmark the rest of the market is valued against. It supplies the daily liquidity that lets large investors move in and out without distorting prices. Strip an exchange of its anchors one at a time and what remains is thinner, more volatile, and harder for a serious institution to take seriously.
The Jamaica Stock Exchange, which is itself a listed company, has spent years trying to attract listings rather than lose them, and the departure of its single most valuable name runs directly against that effort. The exchange will survive it. But every anchor that leaves makes the next departure easier to imagine.
A model others can, and may, follow
Which brings us to the question every chief financial officer in Kingston is now turning over. Can other major companies do what Scotia has done? Mechanically, yes. Any company whose parent already holds a controlling stake can offer to buy out the minority, win a shareholder vote, secure a court sanction, and delist, exactly the path Scotia walked.
The tools are ordinary company law, available to anyone with a majority owner and the cash to pay the minority a premium. There is nothing exotic in the method, which is precisely why it deserves attention now rather than after the fact.
Will they? That depends on the arithmetic that drove Scotia. A foreign parent that takes a profitable Caribbean subsidiary private captures all of its earnings rather than sharing them with outside holders, answers only to its own board, and sheds the cost and the disclosure that a public listing demands. Several of the largest names on the Jamaican and wider Caribbean exchanges are majority-owned by foreign banks and conglomerates for whom that same logic applies cleanly.
Against it sits a real cost, the premium paid to minority holders, and a less visible one, the goodwill a company spends when it withdraws from the local public and from the national project of a home-grown capital market. Some boards will decide the earnings are worth more than the goodwill. The honest forecast, from where St. Jean Money & Markets sits, is that Scotia will not be the last, and that the region's regulators and exchanges should be working now on how to make staying public more attractive than going private, before the question answers itself one company at a time.
What SJMM is watching
I write this through St. Jean Money & Markets, the Caribbean markets desk and data terminal we are building so that this region has the kind of market intelligence institutions elsewhere take for granted, benchmarked against Bloomberg on quality and priced for Caribbean budgets rather than Wall Street ones. SJMM reads these markets at the close of every session, and the positions and the analysis in this piece are its own. That independence is the point.
A market desk is only useful if it reports what it sees rather than what anyone would prefer it saw, and what it sees this week is a strong market quietly losing one of its foundations. The bell will ring on Monday, as it always does. Scotia simply will not answer it, and the exchange, and the country, will spend the next several years learning what it means to run a capital market with one fewer pillar holding up the roof.
Read more at The Caribbean Ledger ›